The coverage your homeowners policy does not include
Flood is excluded from every standard homeowners policy in Alabama. If water rises into your home, whether from storm surge, a swollen creek, or heavy rain with nowhere to go, a flood policy is what responds.
Walker Insurance Agency writes both National Flood Insurance Program policies and private flood coverage. NFIP is the federal program administered through FEMA, sold by agencies like ours but priced by the government. Private flood carriers set their own terms and often offer higher limits, shorter waiting periods, and different pricing. Comparing both is the advantage of working with an independent agency.
What Flood Insurance Covers

Building coverage — The structure itself: foundation, walls, electrical and plumbing systems, furnace and water heater, permanently installed cabinets and flooring, and attached fixtures.
Contents coverage — Your belongings: furniture, clothing, electronics, appliances that are not built in, and personal property.
These are separate purchases, and this is the most common gap we find. Buying building coverage alone leaves everything inside uncovered. Renters can buy contents coverage on its own without building coverage.
What flood policies generally do not cover — Most exclude landscaping, decks and patios outside the structure, vehicles, currency and precious metals, and in many cases the contents of a basement beyond limited categories. Coverage below the lowest floor is restricted under NFIP. Private policies vary, which is part of why comparing them matters.
NFIP or Private Flood
NFIP
Private flood
Who sets the price
The federal government
The individual carrier
Coverage limits
Capped by the program
Often higher, especially on building coverage
Waiting period
Standard federal waiting period
Sometimes shorter
Additional living expenses
Generally not included
Often available
Availability
Nearly universal
Depends on the property
Neither is automatically better. It depends on the property, the flood zone, the elevation, and what you need covered. We quote both and show you the difference.
What This Means in Baldwin County
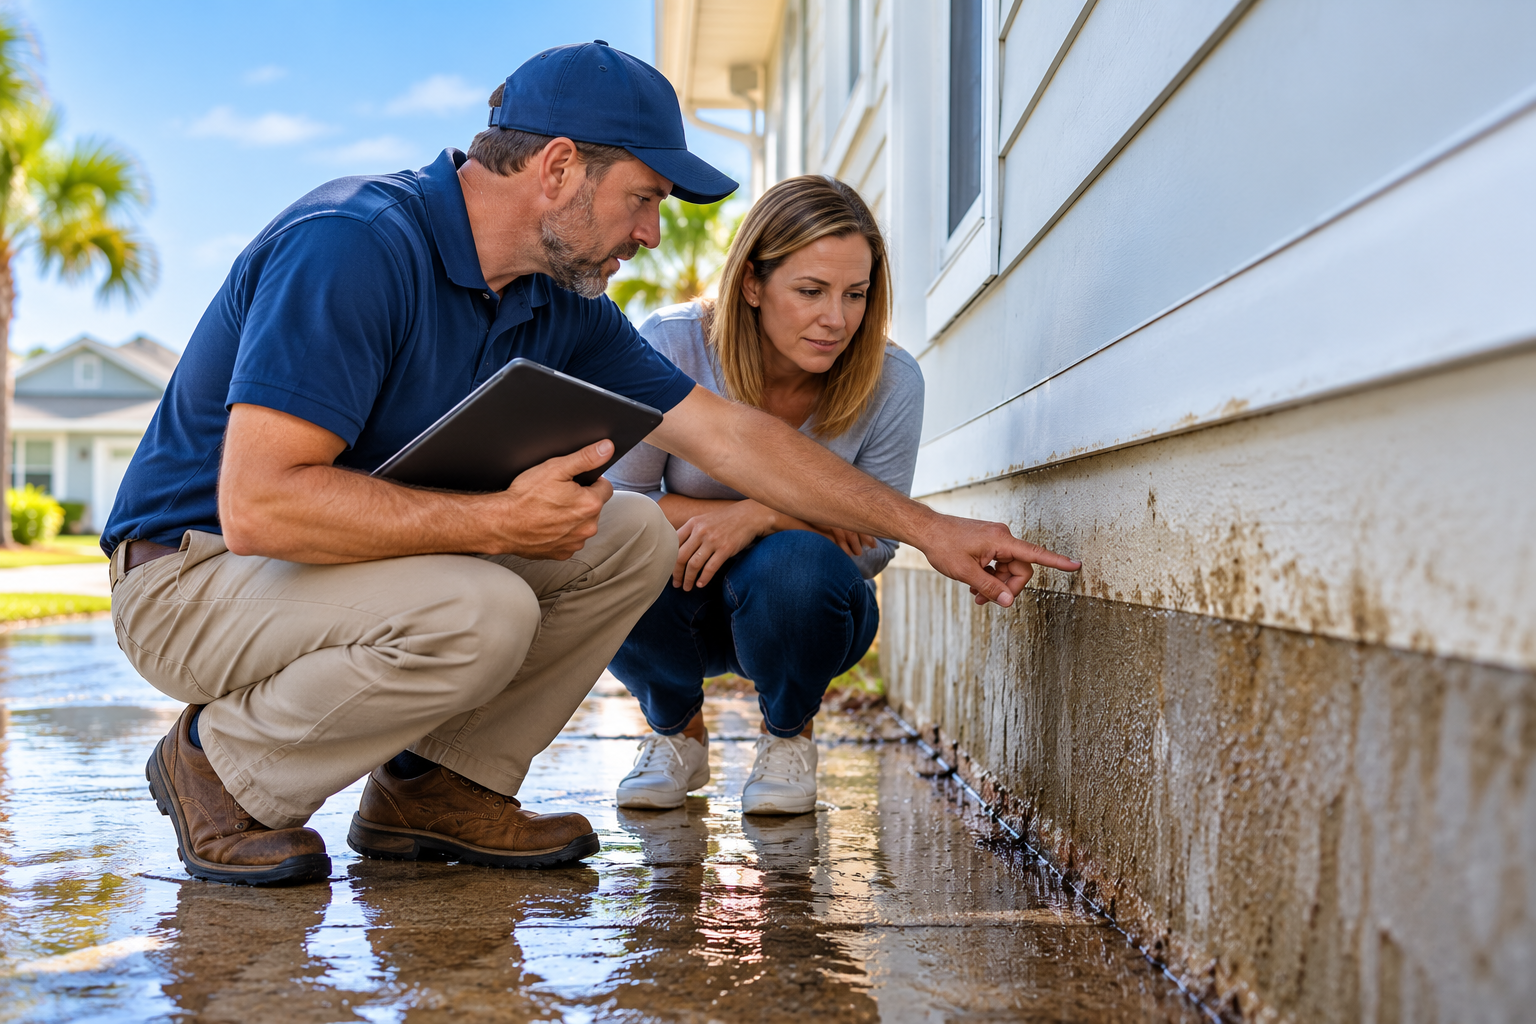
Flood zones tell you what your lender requires, not what can happen. A meaningful share of flood claims come from properties outside high-risk zones. Drainage capacity varies a great deal by neighborhood here, and heavy rainfall events put water places the maps did not anticipate. Being outside a high-risk zone usually means coverage costs less — a reason to buy it rather than skip it.
Storm surge is flood, not wind. This is where coastal claims get contested. Wind damage falls under your homeowners policy; water pushed inland by a storm falls under flood. A hurricane can produce both, and the policies that respond are different. Carrying only one leaves half the exposure open.
The waiting period is the whole game. Flood coverage bought as a storm approaches does not help. Every year people call our office once a system enters the Gulf, and by then the decision has already been made for them. Buy it in the spring.
Elevation drives your price under NFIP. The federal rating system prices by property characteristics, and how high your lowest floor sits relative to expected flood levels is a significant factor. An elevation certificate can be worth obtaining for properties where it may help.
Businesses need it too. Commercial property policies exclude flood the same way homeowners policies do. A flooded building, ruined inventory, and weeks of lost revenue are three separate problems, and a commercial flood policy plus business interruption is what addresses them.
What Affects Your Cost
Flood zone · elevation of the lowest floor · age and construction of the building · presence of a basement or enclosure below the lowest floor · building and contents limits · your deductible · distance to water · prior flood claims on the property · whether the property is a primary residence.
Frequently Asked Questions
Do I need flood insurance if I am not in a flood zone?
Flood zones tell you what your lender requires, not whether your property can flood. A meaningful share of flood claims come from properties outside high-risk zones. Baldwin County gets heavy rainfall events, and drainage capacity varies a great deal by neighborhood. Being outside a mapped high-risk zone usually means coverage is less expensive, which is a reason to buy it rather than skip it.
What is the waiting period for flood insurance?
New flood policies generally do not take effect immediately. There is typically a waiting period, with narrow exceptions such as coverage required in connection with a loan closing. Call our office at (251) 422-9959 for the current waiting period and any exception that may apply to you.
What is the difference between NFIP and private flood insurance?
NFIP is the federal program, with coverage limits and terms set by the government and rates that do not vary by carrier. Private flood carriers set their own limits, terms, and pricing, and frequently offer higher building and contents limits, coverage options NFIP does not include, and in some cases a shorter waiting period. Which is better depends on the property. We quote both.
Does flood insurance cover my belongings?
Building coverage and contents coverage are separate purchases under NFIP. Buying building coverage alone leaves your furniture, electronics, and personal property uncovered. Private policies structure this differently. Make sure you know what you actually bought.
What affects the cost of flood insurance?
Your flood zone, the elevation of the structure, the age and construction of the building, whether there is a basement or enclosure below the lowest floor, your coverage limits and deductible, and, for NFIP, the property-specific characteristics used under the current federal rating system.
Is flood insurance required in Baldwin County?
It depends on your flood zone and your lender. Properties in high-risk zones with a federally backed mortgage are generally required to carry it. Outside those zones it is optional, but plenty of claims come from properties where nobody required it. Call our office at (251) 422-9959 and we will tell you what applies to your address.
Protect Your Home and Family
The waiting period means flood coverage has to be in place before you need it. Tell us your address and we will quote both NFIP and private options.