Built for a riding season that never really ends
Walker Insurance Agency writes motorcycle coverage for riders throughout Baldwin and Mobile County. Cruisers, touring bikes, sport bikes, and trikes.
Motorcycle insurance covers liability if you injure someone or damage property, and physical damage to the bike from a crash, theft, or other covered loss. Where policies differ is what happens to everything that is not the bike itself.
What Motorcycle Insurance Covers

Liability — Injury and property damage you cause to others. Required in Alabama.
Collision — Repairs or replaces the bike after a crash.
Comprehensive — Theft, vandalism, fire, storm damage, and hitting an animal. Motorcycle theft is common enough that this matters even on an older bike.
Uninsured and underinsured motorist — Pays for your injuries when the at-fault driver has no coverage or not enough. On a bike, those injuries tend to be serious.
Medical payments — Covers medical costs for you and your passenger regardless of fault.
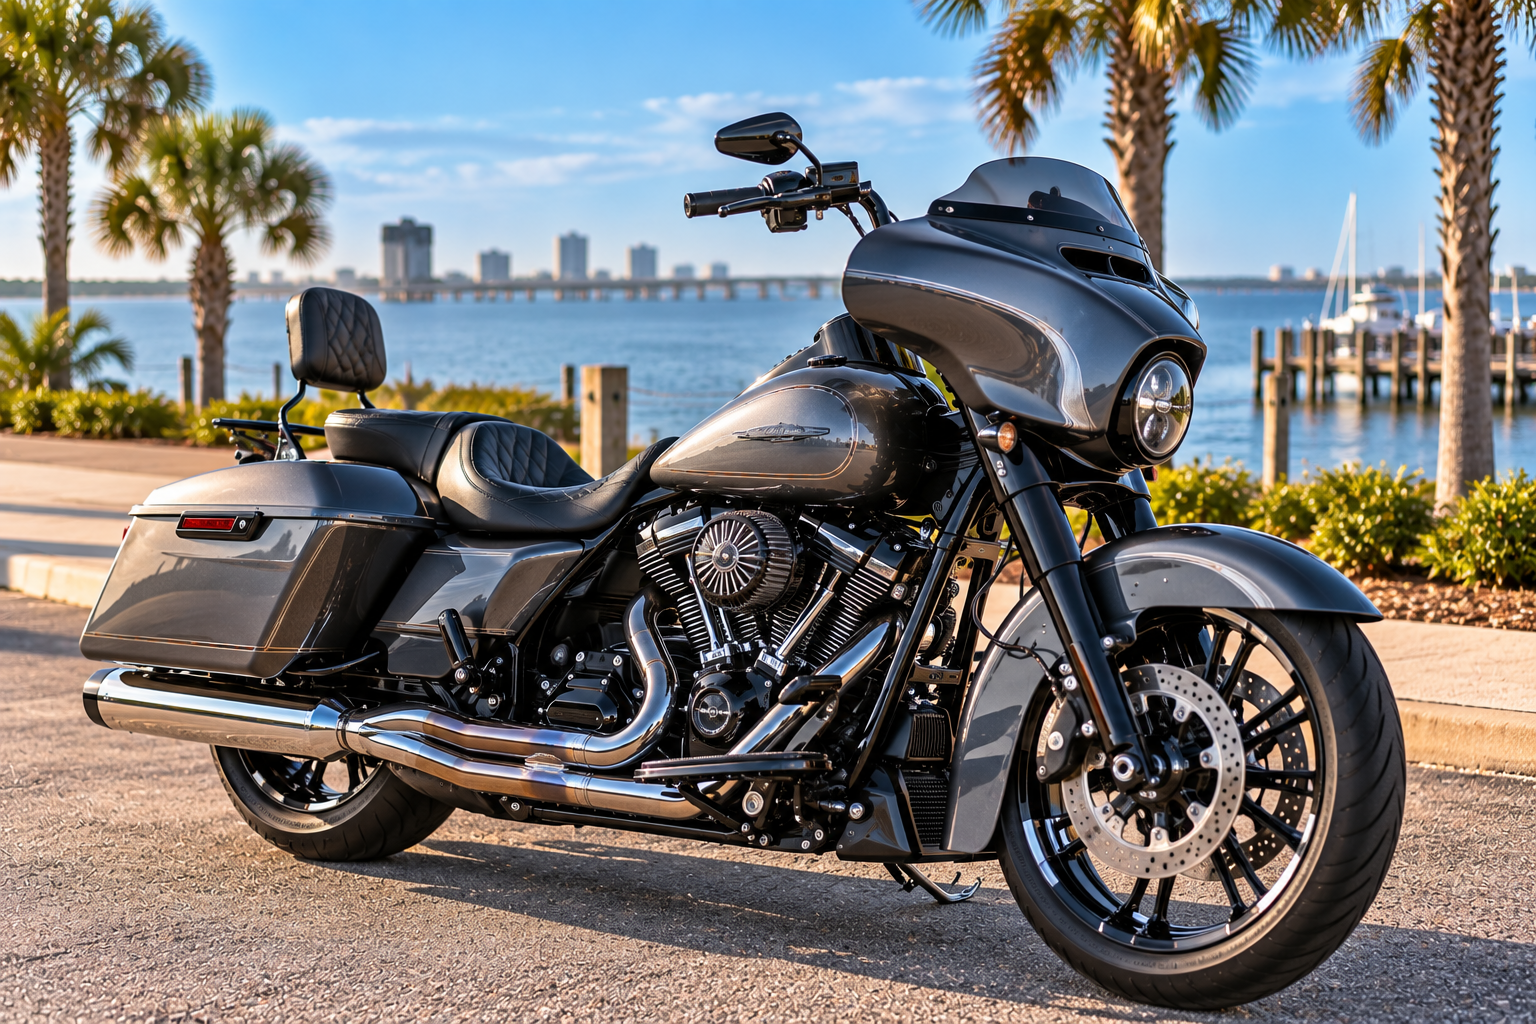
Custom parts and equipment — Exhaust, seats, bags, paint, chrome, and anything else added after it left the dealer.
That last one is what riders most often discover they needed after the fact. Custom work regularly exceeds the standard allowance built into a policy, and the gap is on you unless it was scheduled up front.
What Motorcycle Insurance Covers
Increased custom parts limits — for bikes with significant aftermarket work
Roadside assistance — towing built for a motorcycle rather than a car
Riding gear coverage — helmet, jacket, boots, and gloves, which standard policies often exclude
Trip interruption — lodging and transportation if you break down away from home
Guest passenger liability — confirm whether yours includes it
What This Means on the Gulf Coast
The riding season runs most of the year. More months of riding means more miles and more exposure than a rider in a colder state accumulates. That is an argument for liability limits above the state floor rather than at it.
Uninsured drivers are a real exposure here. Alabama has a persistent uninsured driver problem. A collision between a car and a motorcycle rarely goes well for the rider, and if the at-fault driver has no coverage, uninsured motorist is what responds. It is one of the more valuable coverages on the policy relative to its cost.
Storage matters during hurricane season. A bike parked under a carport or in a garage during a named storm is exposed to wind and flood. Confirm how your policy treats storm damage while the bike is stored, and whether comprehensive responds.
Tourist traffic changes the roads in summer. Highway 59, Highway 98, and the beach routes fill with drivers who do not know the area and are not watching for bikes. More vehicles, more distraction, higher claim severity.
What Affects Your Rate
Type and engine size of the bike, your riding experience and license status, driving and claims record, annual mileage where the bike is stored, and completed safety Courses, custom parts value your limits and deductibles
Carriers weigh these very differently, particularly engine size and rider age, which is where comparing more than 100 carriers produces real differences.
Frequently Asked Questions
Does Alabama require motorcycle insurance?
Yes. Motorcycles are subject to the state’s financial responsibility requirements like other registered vehicles. Confirm current limits with our office. As with auto, state minimums are a floor and not a recommendation.
Are my custom parts and accessories covered?
Only up to the policy’s standard allowance, which is often modest. If you have added exhaust, bags, custom paint, or aftermarket components, list them and add coverage for the value. This is the single most common gap we find on motorcycle policies.
Does my policy cover a passenger?
Guest passenger liability is not automatically included on every motorcycle policy and sometimes has to be added. If you ride two-up, confirm it.
Should I carry uninsured motorist coverage on a motorcycle?
It is worth strong consideration. Motorcycle accidents involving another vehicle tend to produce serious injuries, and if the at-fault driver has no coverage or not enough, this is what responds.
What affects my motorcycle rate?
The type and engine size of the bike, your riding experience and license status, your driving and claims record, annual mileage, where the bike is stored, completed safety courses, and the coverages and deductibles you choose.
Is my riding gear covered if I go down?
Often not under a standard policy. Helmets, jackets, boots, and gloves represent real money, and many policies either exclude them or cover them at a low limit. Gear coverage can usually be added. Tell us what you ride in and we will make sure it is on there.
Are Your Custom Parts Actually Covered
Send us the details on your bike and what you have added to it. We will compare carriers and make sure your custom work, your gear, and your limits all match what you actually ride.