Coverage for your employees and protection for your business
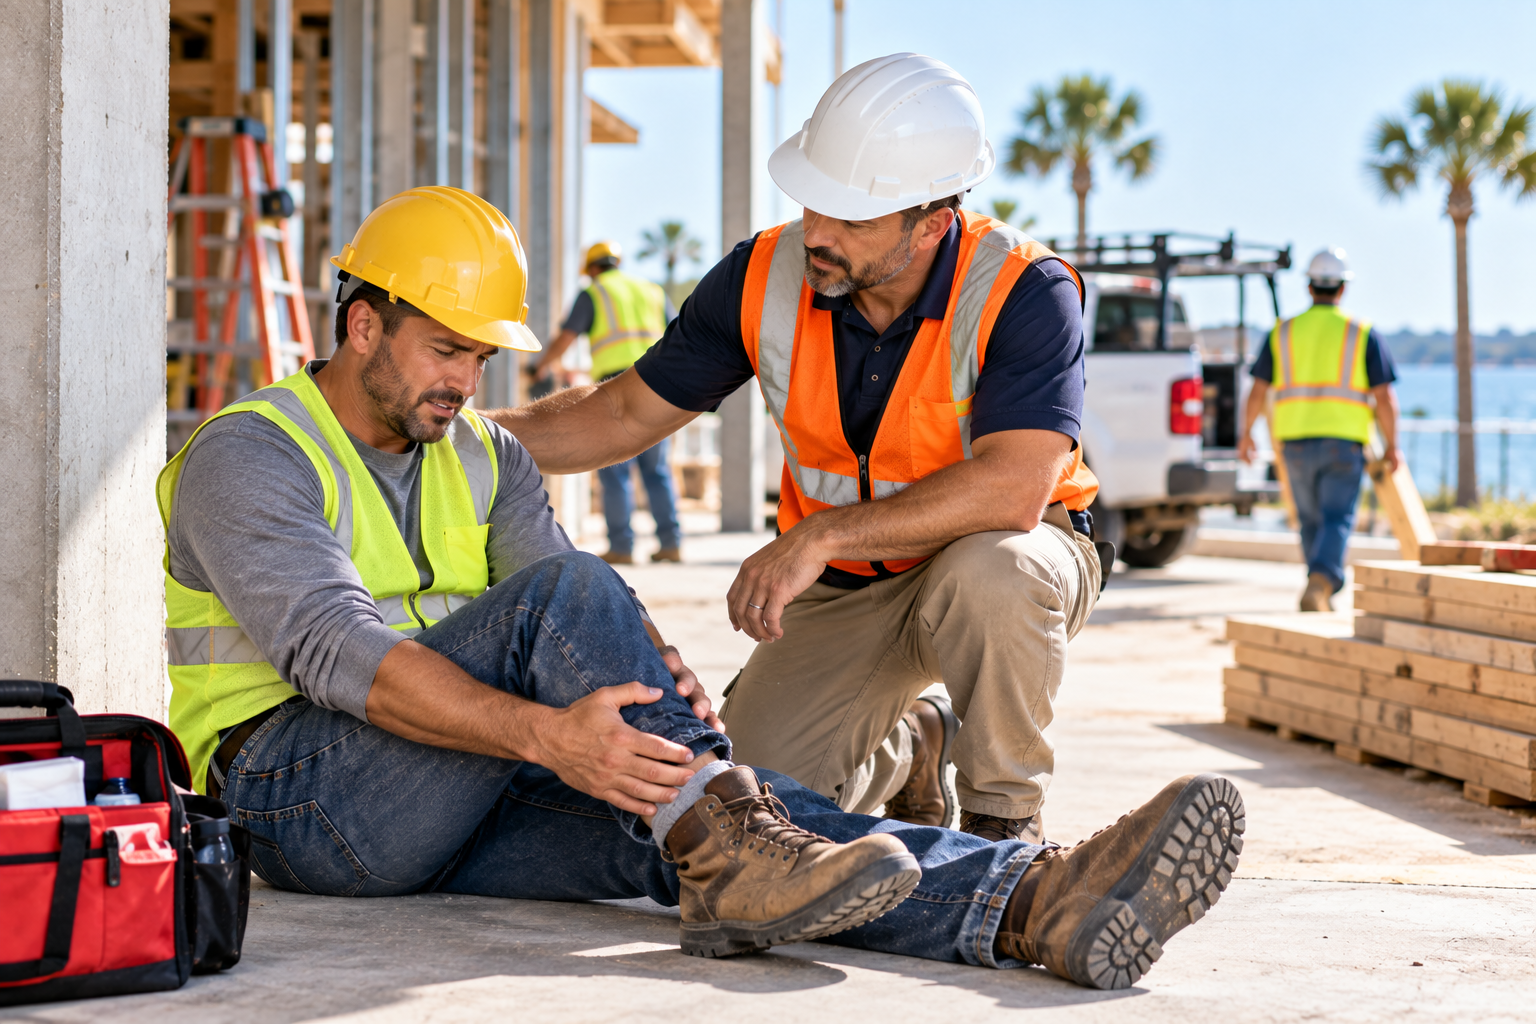
Workers compensation pays medical costs and lost wages when an employee is injured on the job. In exchange, it generally limits the employee’s ability to sue the business over that injury. That second part is why it protects you as much as them.
Walker Insurance Agency writes workers compensation for businesses throughout Mobile and Baldwin County.
Alabama requires most employers above a certain employee count to carry it, with exemptions that vary by industry and business structure. Whether you fall under the requirement depends on how you are organized as much as on headcount. Call our office at (251) 422-9959 and we will work through it with you.
What Workers’ Compensation Covers

Medical treatment — Care for a work-related injury or illness, from an urgent care visit through surgery and rehabilitation.
Lost wages — Partial wage replacement while an injured employee is unable to work.
Permanent disability — Benefits when an injury results in lasting impairment.
Death benefits — Payments to dependents following a fatal workplace accident.
Employer’s liability — Protects the business against injury-related suits that fall outside the workers compensation system.
The Three Things That Drive What You Pay
Class codes set your base rate. Every job function is assigned a classification, and the rates vary enormously between them — clerical work and roofing are not close. Payroll assigned to the wrong code means you are paying the wrong price. Underpaying gets corrected at audit with a bill you did not plan for.
Your experience modification factor compares you to your peers. Below 1.0 lowers your premium, above 1.0 raises it. It is calculated from several years of claims history and it follows you when you change carriers. A clean loss run is worth real money, and improving a mod takes years rather than months, which is why safety programs pay off gradually and then significantly.
Your payroll is an estimate until the audit says otherwise. The policy is issued on projected payroll. At the end of the term the carrier reviews what you actually paid and adjusts. Grow faster than you projected and you owe the difference.
What This Means for Businesses Here
Subcontractor certificates are the expensive lesson. If a sub does not carry their own workers compensation coverage, their payroll can be charged to your policy at audit, and their injuries can become your liability. Collect a certificate before work starts, every time. On a busy Gulf Coast job site this is the single most common and most avoidable audit surprise we see.
Storm rebuild work changes your class codes. A contractor who normally does interior remodels and picks up roofing work after a hurricane has changed their exposure. Tell us when the work you do changes, because the policy needs to reflect it and discovering it at audit is worse.
Seasonal payroll swings need to be reported. Restaurants, retail, and hospitality businesses here staff up dramatically for the season. Payroll projections built on a slow month produce an audit bill in the fall.
Alabama’s requirement depends on structure, not just headcount. Sole proprietors, partners, LLC members, and corporate officers may be treated differently from employees, and some can elect in or out. Getting this wrong in either direction costs money. It is worth a conversation rather than an assumption.
Preparing for the audit is most of the work. Clean payroll records by class code, certificates on file for every sub, and accurate job descriptions turn a stressful audit into a routine one. We help clients get ready before the auditor calls.
What Affects Your Cost
Your class codes and how payroll is distributed across them, total payroll, your experience modification factor, claims history and severity, state where employees work, safety programs and documented training, whether you use subcontractors and whether they carry coverage, your industry, claims history, liability limits and deductibles, and whether the boat is used for charter or business.
Frequently Asked Questions
Does Alabama require workers' compensation insurance?
Alabama requires most employers with a certain number of employees to carry coverage, with exemptions that vary by industry and entity type. Sole proprietors, partners, and certain officers may be treated differently. Confirm your situation by calling our office at (251) 422-9959.
Are subcontractors covered under my policy?
Usually not, and this is a common and expensive surprise. If a subcontractor does not carry their own workers compensation coverage, your policy may be charged for their payroll at audit, and you may carry liability for their injuries. Collect certificates of insurance from every sub, before the work starts.
What is an experience modification factor?
A number comparing your claims history to the average for businesses in your class. Below 1.0 lowers your premium; above 1.0 raises it. It is calculated from several years of history and follows you when you change carriers. Reducing claims takes time to show up, which is why safety programs pay off over years rather than months.
Why do class codes matter so much?
Your class code sets the rate applied to your payroll. Rates vary enormously between classes — clerical work and roofing are not close. Miscoded payroll means you are overpaying or underpaying, and underpaying gets corrected at audit with a bill. Getting the codes right at the start is worth the conversation.
What happens at a premium audit?
Your policy is issued on estimated payroll. At the end of the term, the carrier reviews actual payroll and class assignments and adjusts the premium. If actual payroll was higher, you owe the difference. Keeping accurate records through the year prevents surprises.
What should I do when an employee gets hurt?
Get them medical care first. Then report the claim to the carrier promptly — delayed reporting raises claim costs and can create problems with the claim itself. Document what happened while it is fresh, including witnesses. Stay in contact with the employee through their recovery, because employees who feel abandoned by an employer are considerably more likely to bring an attorney into it. Call our office and we will walk you through the reporting process.
Are Your Class Codes Right
Send us your current declarations page and your last audit. We will check your class codes, look at your experience mod, and tell you whether the policy you have matches the work you actually do.